Understand how an LLP is formed, what the partners need to agree and provide, and what the annual filings involve. We prepare the documents and handle the MCA filings.
What it is. A Limited Liability Partnership is a body corporate registered under the Limited Liability Partnership Act, 2008. It combines the internal flexibility of a partnership with limited liability for its partners.
Typical timeline: commonly 7 to 10 working days from receipt of complete documents. Estimated timelines can vary depending on documentation, government processing and other factors outside our control.
Quick answer
What is an LLP?
A Limited Liability Partnership (LLP) is a body corporate registered under the Limited Liability Partnership Act, 2008. It has a legal identity of its own, and each partner's liability is limited to the contribution they agreed to bring in. Registering one means reserving a name, filing the FiLLiP incorporation form with the Registrar of Companies, and then filing the LLP Agreement within 30 days of incorporation.
Key takeaways
Needs at least two designated partners, both individuals, one of them resident in India.
A partner is not personally liable for another partner's wrongful acts.
Cannot issue equity shares, so it does not suit a business planning to raise venture capital.
Form 8 and Form 11 are due every year, even in a year with no business activity.
How it is structured
Who owns an LLP, who runs it, and who carries the risk
Registering an LLP settles who the partners are, which of them are designated partners answerable for its filings, and how far personal liability reaches. Eligibility, documents and annual compliance all follow from that.
Partners own and run it. Designated partners answer for its compliance.
PARTNERS
LIABILITY SHIELD
Limited Liability Partnership
Separate legal entity
Liability limited to the agreed contribution
Is it right for you?
Who should choose LLP, and where it may not fit.
Worth weighing before you commit, because changing structure later is not free.
A good fit for
Professional practices and consultancies run by two or more partners
Partner-operated businesses that want liability protection without a board structure
Service firms where profit sharing is negotiated rather than fixed by shareholding
Businesses that do not intend to raise equity investment
Existing partnership firms looking to move to a structure with limited liability
!Where it may not fit
Cannot issue equity shares, so it is not suitable if you plan to raise venture capital
Any change in partners or in the LLP Agreement must be filed with the Registrar
Form 8 and Form 11 must be filed annually even in a year with no business activity
Late ROC filing attracts an additional fee that steps up with the length of the delay
An LLP is a body corporate in its own right. It can hold property, enter contracts and sue or be sued in its own name, independent of the partners who make it up.
Limited liability for partners
A partner's liability is limited to their agreed contribution. A partner is not personally liable for the wrongful acts of another partner, which is the key difference from a traditional partnership firm.
Flexible internal arrangement
Profit sharing, management rights, admission and exit of partners are governed by the LLP Agreement, which the partners negotiate among themselves rather than taking from a statutory template.
Lighter compliance than a company
There is no requirement to hold board or general meetings, and audit is required only once turnover or contribution crosses the statutory thresholds.
Perpetual succession
The LLP continues despite changes in its partners. Partners can be admitted or can retire without the entity itself coming to an end.
Eligibility
What you need to qualify.
1A minimum of two partners. There is no upper limit on the number of partners.
2A minimum of two designated partners, both individuals, at least one of whom must be a resident of India.
3Each designated partner needs a DPIN or DIN and a valid Class 3 Digital Signature Certificate.
4A registered office address in India with valid proof and a no-objection certificate where the premises are not owned.
5An agreed capital contribution from each partner. There is no statutory minimum contribution.
6A proposed name that is not identical or deceptively similar to an existing company, LLP or registered trade mark.
Requirements vary with the people involved and the premises. We confirm the exact list before anything is prepared.
6 stages, what happens at each, and who acts. Select a step to see the detail.
STEP 1 OF 6 · RAULJI GROUP ARRANGES
Digital Signature Certificate
Class 3 DSCs are obtained for the designated partners, since every form filed with the Registrar of Companies is signed digitally.
STEP 2 OF 6 · REGISTRAR DECIDES
Name reservation (RUN-LLP)
The proposed name is reserved through the RUN-LLP service on the MCA portal. We check availability and screen against registered trade marks before applying, and keep an alternative ready.
STEP 3 OF 6 · RAULJI GROUP FILES
Incorporation filing (FiLLiP)
The FiLLiP form covers the partners, designated partners, capital contribution and registered office. DPIN can be applied for within this same form for partners who do not already hold one.
STEP 4 OF 6 · REGISTRAR ISSUES
Certificate of Incorporation
The Registrar issues the Certificate of Incorporation with the LLP Identification Number. The LLP exists as a body corporate from the date on that certificate.
STEP 5 OF 6 · PARTNERS SIGN, WE FILE
LLP Agreement (Form 3)
The LLP Agreement sets out profit sharing, duties, decision-making and the process for admitting or removing partners. It must be executed on stamp paper of the value prescribed by the relevant state and filed in Form 3 within 30 days of incorporation.
STEP 6 OF 6 · YOU, WITH OUR SUPPORT
PAN, TAN and operating registrations
PAN and TAN are applied for, a current account is opened, and any further registrations your activity requires, such as GST, are taken up.
Timeline
How long does registration take?
Commonly 7 to 10 working days from receipt of complete documents.
An estimate, not a commitment. Estimated timelines can vary depending on documentation, government processing and other factors outside our control.
Our part
Digital signatures, name screening, the FiLLiP filing and drafting the LLP Agreement. This starts once every document is complete.
The authority’s part
Name reservation and incorporation are processed by the Registrar. A query or a name rejection adds a round trip that nobody outside the Registrar can shorten.
What we handle
Every filing, from signature to certificate.
DSC issuance for designated partners
Name availability and trade mark screening before filing
RUN-LLP name reservation
FiLLiP incorporation filing, including DPIN applications
Drafting the LLP Agreement to reflect what the partners have agreed
Form 3 filing of the LLP Agreement within the 30-day window
PAN and TAN applications
Responding to Registrar queries or resubmission requests
What you provide
Identity and address documents for every partner
The proposed LLP name, with a second option
Each partner's capital contribution
The terms for the LLP Agreement: profit share, roles, decisions, admission and exit
Registered office proof and the owner's no-objection certificate
Time for DSC verification and for signing the filings and the agreement
Pricing
What makes up the total.
Two kinds of money are involved: our professional fee, and the government and state charges we do not set. Nothing on this page is an all-inclusive price.
Professional feeSet by Raulji Group
₹7,999, one time, for the work listed in the package.
Government filing feesSet by Ministry of Corporate Affairs
Depend on the total capital contribution. Paid to the MCA at filing.
Stamp duty on the LLP AgreementSet by State government
At the rate of the state where the LLP is registered.
TaxesSet by As applicable
Any tax that applies to the professional fee is shown in the written quote.
We confirm the full expected amount, split this way, in writing before any filing begins.
Next steps
What happens after registration?
Registration starts the obligations rather than ending them. These are the ones that follow for this structure.
STEP 1
File the LLP Agreement
The agreement is executed on stamp paper at the state's rate and filed in Form 3 within 30 days of incorporation. Late filing attracts an additional fee that increases with the length of the delay.
STEP 2
PAN, TAN and a current account
The LLP gets its own PAN and TAN, and a current account is opened in its name against the Certificate of Incorporation.
STEP 3
Registrations for your activity
GST, a shop and establishment registration or an activity licence, depending on what the LLP actually does and where.
STEP 4
Run the annual cycle
Form 11 by 30 May and Form 8 by 30 October, every year. Accounts are audited once turnover exceeds ₹40 lakh or contribution exceeds ₹25 lakh.
A Limited Liability Partnership is a body corporate registered under the LLP Act, 2008. It has a legal identity separate from its partners, so it can own property and contract in its own name, while partners are liable only to the extent of the contribution they have agreed to bring in.
Who should choose an LLP?
An LLP suits a business run by the people who own it, where profit sharing is negotiated between partners and there is no plan to raise equity investment. Professional practices, consultancies and partner-operated service firms are common examples. If you expect to take on investors, a Private Limited Company is the more workable structure.
How many partners are required?
At least two partners, with no upper limit. At least two of them must be designated partners, who must be individuals and carry the responsibility for statutory compliance, and at least one designated partner must be a resident of India.
What are designated partners?
Designated partners are the partners specifically responsible for the LLP's compliance obligations, including its ROC filings. They must hold a DPIN and a digital signature. Every LLP needs at least two, and at least one must be resident in India. Ordinary partners share in profits and management without carrying that statutory responsibility.
What documents are required?
PAN, Aadhaar, identity proof, recent address proof in the partner's own name and a photograph for each partner, along with proof of the registered office address, a rent agreement if the premises are rented and a no-objection certificate from the owner.
What is the LLP registration process?
Digital signatures are obtained for the designated partners, the name is reserved through RUN-LLP, the FiLLiP incorporation form is filed with the Registrar, the Certificate of Incorporation is issued with an LLPIN, and the LLP Agreement is executed on stamp paper and filed in Form 3 within 30 days of incorporation.
Is the LLP Agreement mandatory?
Yes. The LLP Agreement must be filed in Form 3 within 30 days of incorporation. If no agreement is filed, the default provisions in the First Schedule to the LLP Act apply, which divide profits and management rights equally regardless of what the partners actually intended.
How is an LLP different from a Private Limited Company?
An LLP cannot issue equity shares or create an ESOP pool, which rules it out for venture funding. In exchange it carries lighter compliance: no board or general meetings, and audit only once turnover exceeds ₹40 lakh or contribution exceeds ₹25 lakh. A Private Limited Company requires a statutory audit from its first year regardless of turnover.
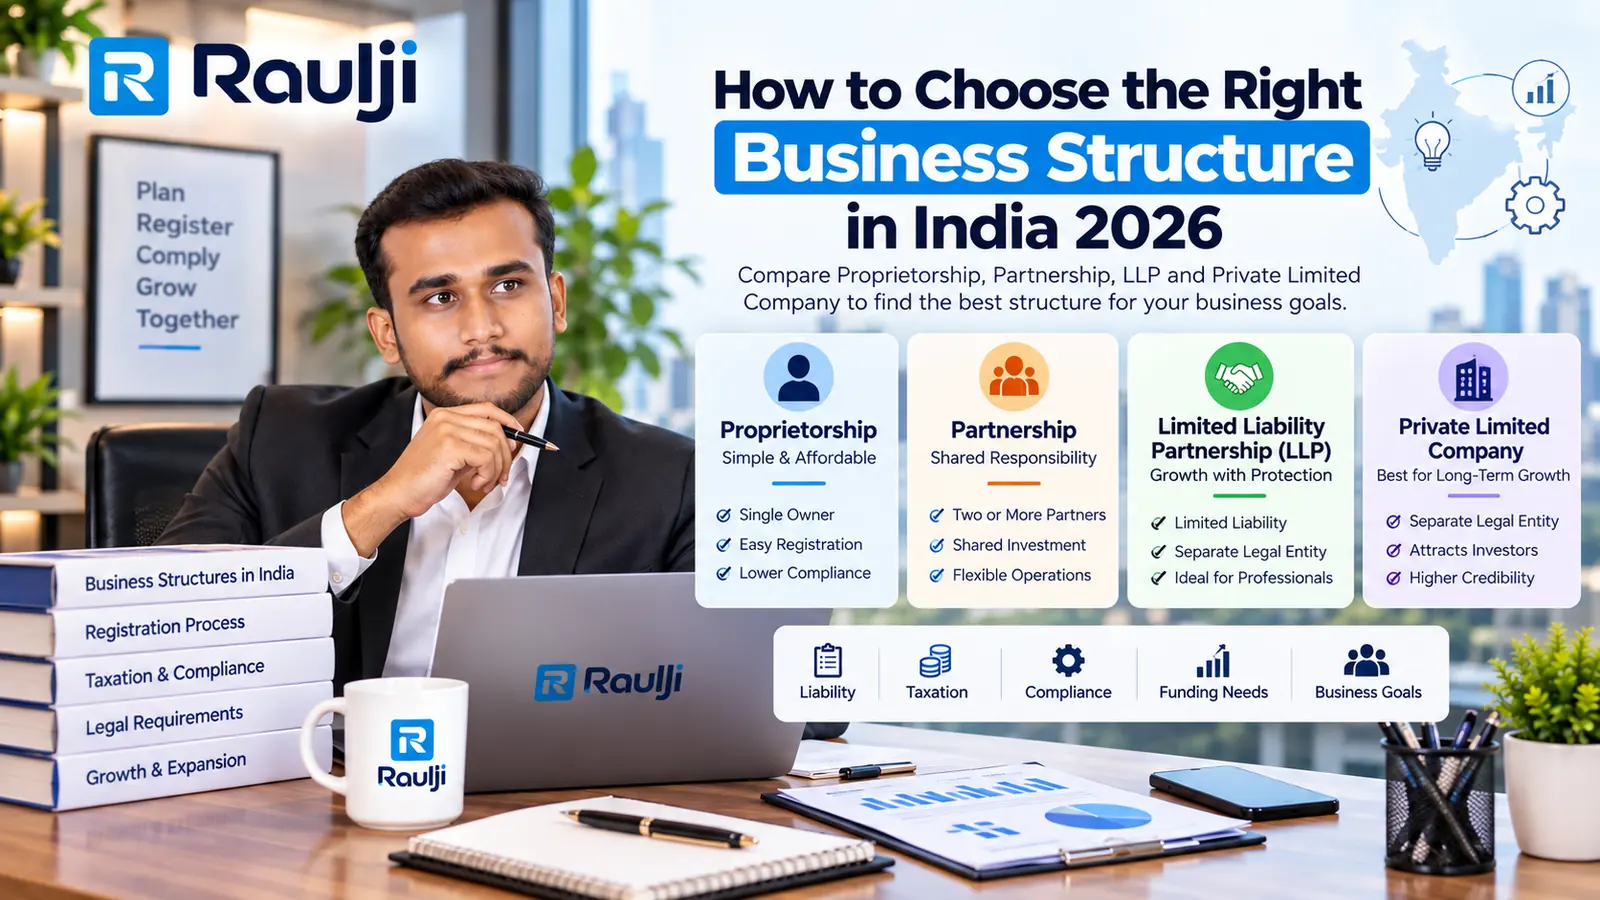
How is an LLP different from a partnership firm?
A partnership firm under the Indian Partnership Act, 1932, is not a separate legal entity and its partners carry unlimited personal liability, including for each other's acts. An LLP is a body corporate with limited liability, and a partner is not personally liable for another partner's wrongful acts. An LLP must file annually with the Registrar of Companies, which a partnership firm does not.
What annual filings does an LLP have?
Form 11, the annual return, is due by 30 May each year, and Form 8, the statement of account and solvency, by 30 October. Both are due even in a year with no business activity. Accounts must be audited if turnover exceeds ₹40 lakh or contribution exceeds ₹25 lakh. Late filing attracts an additional fee that steps up with the length of the delay.