Understand what the partnership deed must cover, how registration with the Registrar of Firms works, and what partners take on. We draft the deed and handle the registration.
What it is. A partnership firm is a business owned by two or more people who have agreed to share its profits, governed by the Indian Partnership Act, 1932. The firm is not a separate legal entity from its partners.
Typical timeline: the deed can usually be drafted and executed within a few working days. Registrar of Firms processing time varies from state to state. Estimated timelines can vary depending on documentation, government processing and other factors outside our control.
Quick answer
What is a Partnership Firm?
A partnership firm is a business carried on by two or more people who have agreed to share its profits, under the Indian Partnership Act, 1932. It is not a separate legal entity, and the partners are personally liable for the firm's debts without limit. The firm is formed by a partnership deed. Registering it with the state's Registrar of Firms is optional in law but advisable, because an unregistered firm cannot sue to enforce its contracts.
Key takeaways
Formed by a signed deed between at least two partners. There is no MCA incorporation.
Partners carry unlimited personal liability, including for each other's acts.
Registration is optional, but section 69 limits what an unregistered firm can do in court.
No annual ROC filings. The firm files its own income tax return.
How it is structured
Who owns a partnership firm, who runs it, and who carries the risk
A partnership firm is its partners, working together under a deed. The deed settles who contributes what, who shares the profit and who decides, but nothing separates the business from the people behind it.
The partners own and run it, and carry its debts personally.
PARTNERS
NO LIABILITY SHIELD
Partnership Firm
Not a separate legal entity
Partners’ liability is unlimited and joint
Is it right for you?
Who should choose Partnership, and where it may not fit.
Worth weighing before you commit, because changing structure later is not free.
A good fit for
Two or more people starting a business together with shared capital and effort
Family businesses and trading concerns that want a simple, low-cost structure
Local businesses that do not need limited liability or outside investment
Businesses that want to start operating quickly with minimal statutory filing
Partners who may later convert to an LLP once the business settles
!Where it may not fit
Partners carry unlimited personal liability, so personal assets can be used to meet the firm's debts
Each partner is liable for business acts done by the other partners in the firm's name
The firm is not a separate legal entity and generally cannot hold property in its own name
An unregistered firm cannot sue to enforce a contractual right in court, under section 69 of the Act
Equity investment cannot be raised, so the structure does not suit a business seeking funding
A partnership comes into existence through the partnership deed the partners sign. There is no incorporation application to the Ministry of Corporate Affairs and no waiting on a central approval.
Low cost to set up and run
The main costs are deed drafting, the stamp duty set by the state and, if you register, the Registrar of Firms fee. There are no annual ROC filings and no mandatory statutory audit.
Flexible internal terms
Capital, profit sharing ratios, drawings, responsibilities and the process for admitting or retiring a partner are whatever the partners write into the deed.
Direct control
The partners run the business themselves. There is no board, no separate shareholder layer and no requirement to hold formal meetings or record minutes.
Straightforward tax treatment
The firm is taxed as a separate assessee at the rate applicable to firms. Partners are not taxed again on their share of the firm's profits, though interest and remuneration received from the firm are taxable in their own hands.
Eligibility
What you need to qualify.
1A minimum of two partners, each competent to contract under Indian law.
2A maximum of 50 partners, as prescribed under the Companies Act rules.
3A written partnership deed setting out the terms agreed between the partners.
4Stamp duty on the deed at the rate prescribed by the state where it is executed.
5A place of business, with address proof and a no-objection certificate where the premises are rented.
6A firm name that does not suggest government patronage and does not infringe an existing trade mark.
Requirements vary with the people involved and the premises. We confirm the exact list before anything is prepared.
6 stages, what happens at each, and who acts. Select a step to see the detail.
STEP 1 OF 6 · PARTNERS DECIDE
Agree the commercial terms
Partners settle capital contribution, profit and loss sharing ratios, remuneration and interest on capital, roles, banking authority and what happens when a partner joins, retires or dies.
STEP 2 OF 6 · RAULJI GROUP DRAFTS
Draft the partnership deed
Those terms are written into a deed. A deed that is vague about profit sharing, drawings or exit is the single most common source of later disputes between partners, so this is the step worth spending time on.
STEP 3 OF 6 · PARTNERS SIGN
Stamp and execute the deed
The deed is executed on stamp paper of the value prescribed by the relevant state and signed by all partners in the presence of witnesses. Stamp duty rates differ from state to state.
STEP 4 OF 6 · RAULJI GROUP APPLIES
Apply for the firm's PAN
The firm applies for its own PAN in the firm's name, which the bank will require to open a current account in the name of the business.
STEP 5 OF 6 · REGISTRAR OF FIRMS DECIDES
Register with the Registrar of Firms
Registration is optional but strongly advisable. The application is made in the prescribed form to the Registrar of Firms for the state, with the deed and the required proofs, and a certificate of registration follows.
STEP 6 OF 6 · YOU, WITH OUR SUPPORT
Open the bank account and take operating registrations
A current account is opened in the firm's name, and any registrations your activity needs, such as GST or a shop and establishment licence, are applied for.
Timeline
How long does registration take?
The deed can usually be drafted and executed within a few working days. Registrar of Firms processing time varies from state to state.
An estimate, not a commitment. Estimated timelines can vary depending on documentation, government processing and other factors outside our control.
Our part
Drafting the deed once the partners have settled their terms, then the PAN and Registrar applications. Agreeing the terms usually takes longer than writing them down.
The authority’s part
Registrar of Firms processing, which varies from state to state.
What we handle
Every filing, from signature to certificate.
Advising on the terms that should be covered in the deed
Drafting the partnership deed
Guidance on the correct stamp duty for the state of execution
PAN application in the firm's name
Preparing and filing the application with the Registrar of Firms
Guidance on current account opening documentation
Advising on whether GST registration is applicable to your activity
What you provide
Identity and address documents for every partner
The firm name and the business activity
Each partner's capital, profit share and any remuneration or interest on capital
Who operates the bank account and signs for the firm
What happens when a partner joins, retires or dies
Place of business proof and the owner's no-objection certificate
Pricing
What makes up the total.
Two kinds of money are involved: our professional fee, and the government and state charges we do not set. Nothing on this page is an all-inclusive price.
Professional feeSet by Raulji Group
Quoted once we know what the deed involves and which registrations your activity needs.
Stamp duty on the deedSet by State government
Set by the state where the deed is executed.
Registrar of Firms feeSet by State government
Set by the state. Payable only if the firm is registered.
Operating registrationsSet by Various authorities
GST registration has no government fee. Shop and establishment fees are set locally.
We confirm the full expected amount, split this way, in writing before any filing begins.
Next steps
What happens after registration?
Registration starts the obligations rather than ending them. These are the ones that follow for this structure.
STEP 1
PAN and a current account
The firm applies for a PAN in its own name, which the bank needs to open a current account in the firm's name.
STEP 2
Registrations for your activity
GST where turnover or the type of supply requires it, and a shop and establishment registration for the premises.
STEP 3
The firm's income tax return
The firm is assessed separately at the rate for firms. A tax audit applies once turnover crosses the Income Tax threshold.
STEP 4
Keep the register accurate
Changes in partners, the firm name or the place of business are notified to the Registrar of Firms so the registered details match the firm.
Important considerations
Common mistakes to avoid.
The problems we see most often with a Partnership Firm, and how to avoid each one.
A deed that is vague on money and exit
Profit share, drawings, interest on capital and what happens when a partner leaves are where partnership disputes start. The default rules in the Act may not be what anyone intended.
Skipping registration
An unregistered firm cannot go to court to recover money a customer owes it. Registering later is possible, but a dispute rarely waits.
Underestimating personal liability
Every partner is liable for the firm's debts, including those created by another partner acting for the firm.
Under-stamping the deed
A deed on stamp paper of the wrong value can be refused as evidence until the shortfall and a penalty are paid.
Comparison
Partnership vs Proprietorship
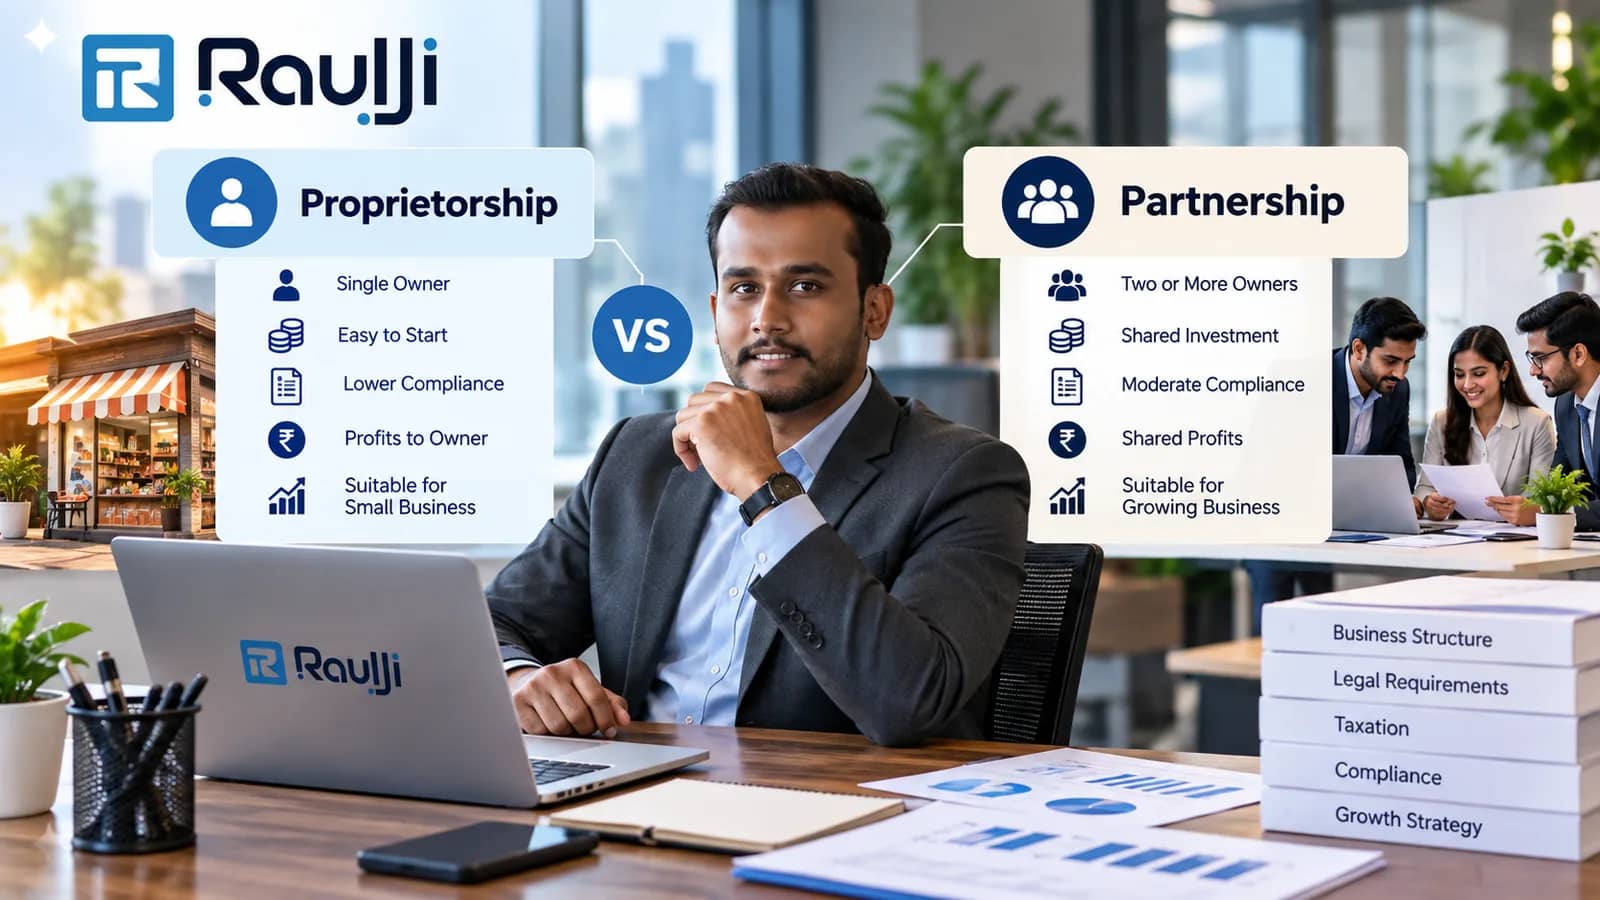
The two unincorporated structures. The difference is how many owners there are and who shares the liability.
Partnership
Proprietorship
vs
Ownership
Partnership: Minimum 2 partners, maximum 50
Proprietorship: A single owner only. Co-owners are not possible.
Management
Partnership: Run directly by the partners, on the terms written into the partnership deed.
Proprietorship: Run by the owner alone. There is no separate management layer.
Liability
Partnership: Unlimited and joint. Partners are personally liable, including for each other's acts in the firm's name.
Proprietorship: Unlimited. Personal assets are exposed to every business debt.
Compliance
Partnership: Low. No annual ROC filing. Income tax return and any GST obligations apply.
Proprietorship: Lowest. No ROC filing. Obligations follow the registrations held, plus the proprietor's own income tax return.
Funding
Partnership: No. Capital can only come from existing or newly admitted partners.
Proprietorship: No. There is no mechanism to bring in an investor without changing structure.
Typical use
Partnership: Two or more people starting together at low cost, where limited liability is not the priority
Proprietorship: A single owner starting small, with limited liability exposure and no plan to bring in partners
Talk to us
Talk to us about Partnership.
Send your details and we will come back to you on what your business actually needs, what it will cost, and how long it is likely to take.
A partnership firm is a business carried on by two or more people who have agreed to share its profits, under the Indian Partnership Act, 1932. The firm is not a separate legal entity, so in law the partners collectively are the business, and they are personally responsible for its obligations.
How many partners are required?
At least two. The maximum is 50 partners, as prescribed under the rules made under the Companies Act. Every partner must be competent to contract, so a minor cannot be a partner, although a minor can be admitted to the benefits of a partnership with the consent of all partners.
What is a partnership deed?
The partnership deed is the written agreement between the partners. It records capital contributions, profit and loss sharing ratios, remuneration and interest on capital, each partner's duties and authority, banking arrangements, and how a partner is admitted, retires or is removed. Where the deed is silent, the default provisions of the Partnership Act apply, which may not be what the partners intended.
Is partnership registration mandatory?
No. The Indian Partnership Act, 1932, does not compel registration, and a firm can legally operate without it. However, section 69 prevents an unregistered firm or its partners from suing to enforce a contractual right against the firm or against a third party. In practice that means an unregistered firm cannot go to court to recover money a customer owes it, so we recommend registering.
What documents are needed?
PAN, Aadhaar, identity proof, address proof and a photograph for each partner, the partnership deed executed on stamp paper, proof of the firm's place of business, a rent agreement if the premises are rented, and a no-objection certificate from the owner.
What is the registration process?
The partners agree their terms, a deed is drafted and executed on stamp paper of the value prescribed by the state, the firm applies for its own PAN, and an application is filed with the Registrar of Firms for the state with the deed and supporting proofs. The Registrar issues a certificate of registration on approval.
How is a partnership firm different from an LLP?
The difference that matters most is liability. In a partnership firm the partners are personally liable without limit, including for the acts of the other partners. In an LLP, liability is limited to the agreed contribution and a partner is not personally liable for another partner's wrongful acts. An LLP is also a separate legal entity and can hold property in its own name, but it carries annual ROC filing obligations that a partnership firm does not.
Can a partnership firm be converted into an LLP or a company later?
Yes. The LLP Act and the Companies Act both provide routes for converting a registered partnership firm into an LLP or into a company, subject to conditions including the consent of all partners. Many firms start as a partnership and convert once the business grows or once limited liability becomes a real concern.
How is a partnership firm taxed?
The firm is assessed to income tax as a separate entity at the rate applicable to firms, plus applicable surcharge and cess. A partner's share of the firm's profit is exempt in the partner's own hands because it has already been taxed in the firm, but interest on capital and remuneration received from the firm are taxable for the partner, and are deductible for the firm only within the limits set by section 40(b).
We would like to measure how people find and use this site, so we can tell which pages genuinely help. Nothing is measured until you choose. We never send your name, phone number, email or enquiry message to any analytics service. Read our privacy policy. Pressing Escape declines.